Ghana's banks are lending, but high loan defaults driving up borrowing costs, says banking chief
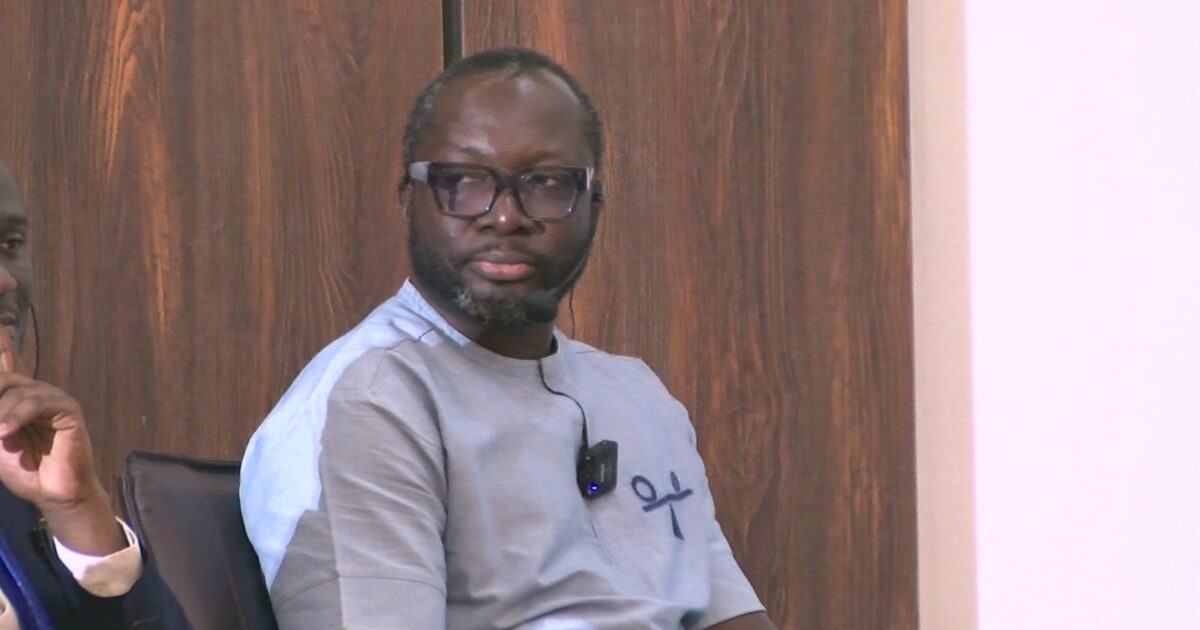
Ghana's banking sector is responding positively to improving monetary conditions and is actively lending to the private sector, according to John Awuah, Chief Executive Officer of the Ghana Association of Banks. Speaking at a post-Monetary Policy Committee discussion in Accra, Awuah pushed back against perceptions that banks are reluctant to extend credit, presenting evidence of strong lending activity despite persistent economic challenges.
The banking chief cited the Bank of Ghana's latest data showing private sector credit grew by 29 per cent year-on-year in real terms, demonstrating that financial intermediation remains robust. More significantly, he highlighted that commercial lending rates have continued to decline even as the central bank held its monetary policy rate steady at 14 per cent since March. Average lending rates fell from above 18 per cent in March to approximately 15.9 per cent by September, whilst new loans are being offered at rates between 9 and 12 per cent—a substantial improvement in borrowing conditions.
The persistent NPL problem constraining credit expansion
However, Awuah's optimistic assessment comes with a significant caveat: Ghana's banking sector continues to grapple with an alarmingly high non-performing loan (NPL) ratio of approximately 15.8 per cent—meaning banks lose roughly 16 cedis for every 100 cedis lent. This stands in sharp contrast to regional peers. Togo's NPL ratio sits below 10 per cent, Côte d'Ivoire's is under 7 per cent, and Nigeria's hovers below 9 per cent. The disparity reveals a structural weakness in Ghana's credit environment that undermines the sector's ability to offer more competitive rates.
The cost of defaults directly affects banks' risk assessment and pricing decisions. When a significant portion of loans default, financial institutions must either absorb losses or pass the cost to borrowing customers through higher interest rates. This creates a vicious cycle: elevated borrowing costs reduce demand for credit among viable businesses and entrepreneurs, whilst constraining economic growth and worsening overall creditworthiness.
Why this matters for Ghana's economic growth
Awuah's intervention highlights a critical debate for Ghana's development agenda. Whilst the central bank controls the policy rate, the real cost of borrowing—what businesses and individuals actually pay—is shaped by underlying risk factors and structural inefficiencies in the financial system. For Ghana's economy to sustain growth and create employment, the banking sector must be able to channel funds to productive enterprises at affordable rates. This is only possible if default rates decline.
The banking chief pointed to legal and institutional gaps as key culprits. Although the Borrowers and Lenders Act provides a framework for collateral enforcement, the recovery process is often delayed by court challenges, increasing lender risk and pushing up interest rates charged to new borrowers. He called for faster, more efficient mechanisms for resolving loan disputes and recovering collateral—not as punitive measures against borrowers, but as systemic improvements that enable banks to lend more confidently and competitively.
Awuah also emphasised the need for collaboration among policymakers, regulators, the judiciary, and business support institutions to address structural weaknesses in the operating environment. High default rates often reflect not just borrower irresponsibility, but broader challenges in business sustainability—weak supply chains, inadequate infrastructure, regulatory uncertainty, and cash flow constraints. Banks can only address the credit supply side; tackling the demand-side challenges requires coordinated action across the economy.
The banking chief's message is clear: Ghana's high borrowing costs are not primarily a banking sector problem, but a system-wide challenge. Banks want to lend at competitive rates and will do so once the risks associated with lending diminish. Until policymakers and stakeholders address the NPL crisis and structural inefficiencies, businesses and individuals will continue paying some of the highest borrowing rates in West Africa.
Source: MyJoyOnline

Comments (0)
Be the first to comment.