
Banking Sector Collapse (2017–2019): Was Ghana's 'Financial House Cleaning' Reform or Political Purge?
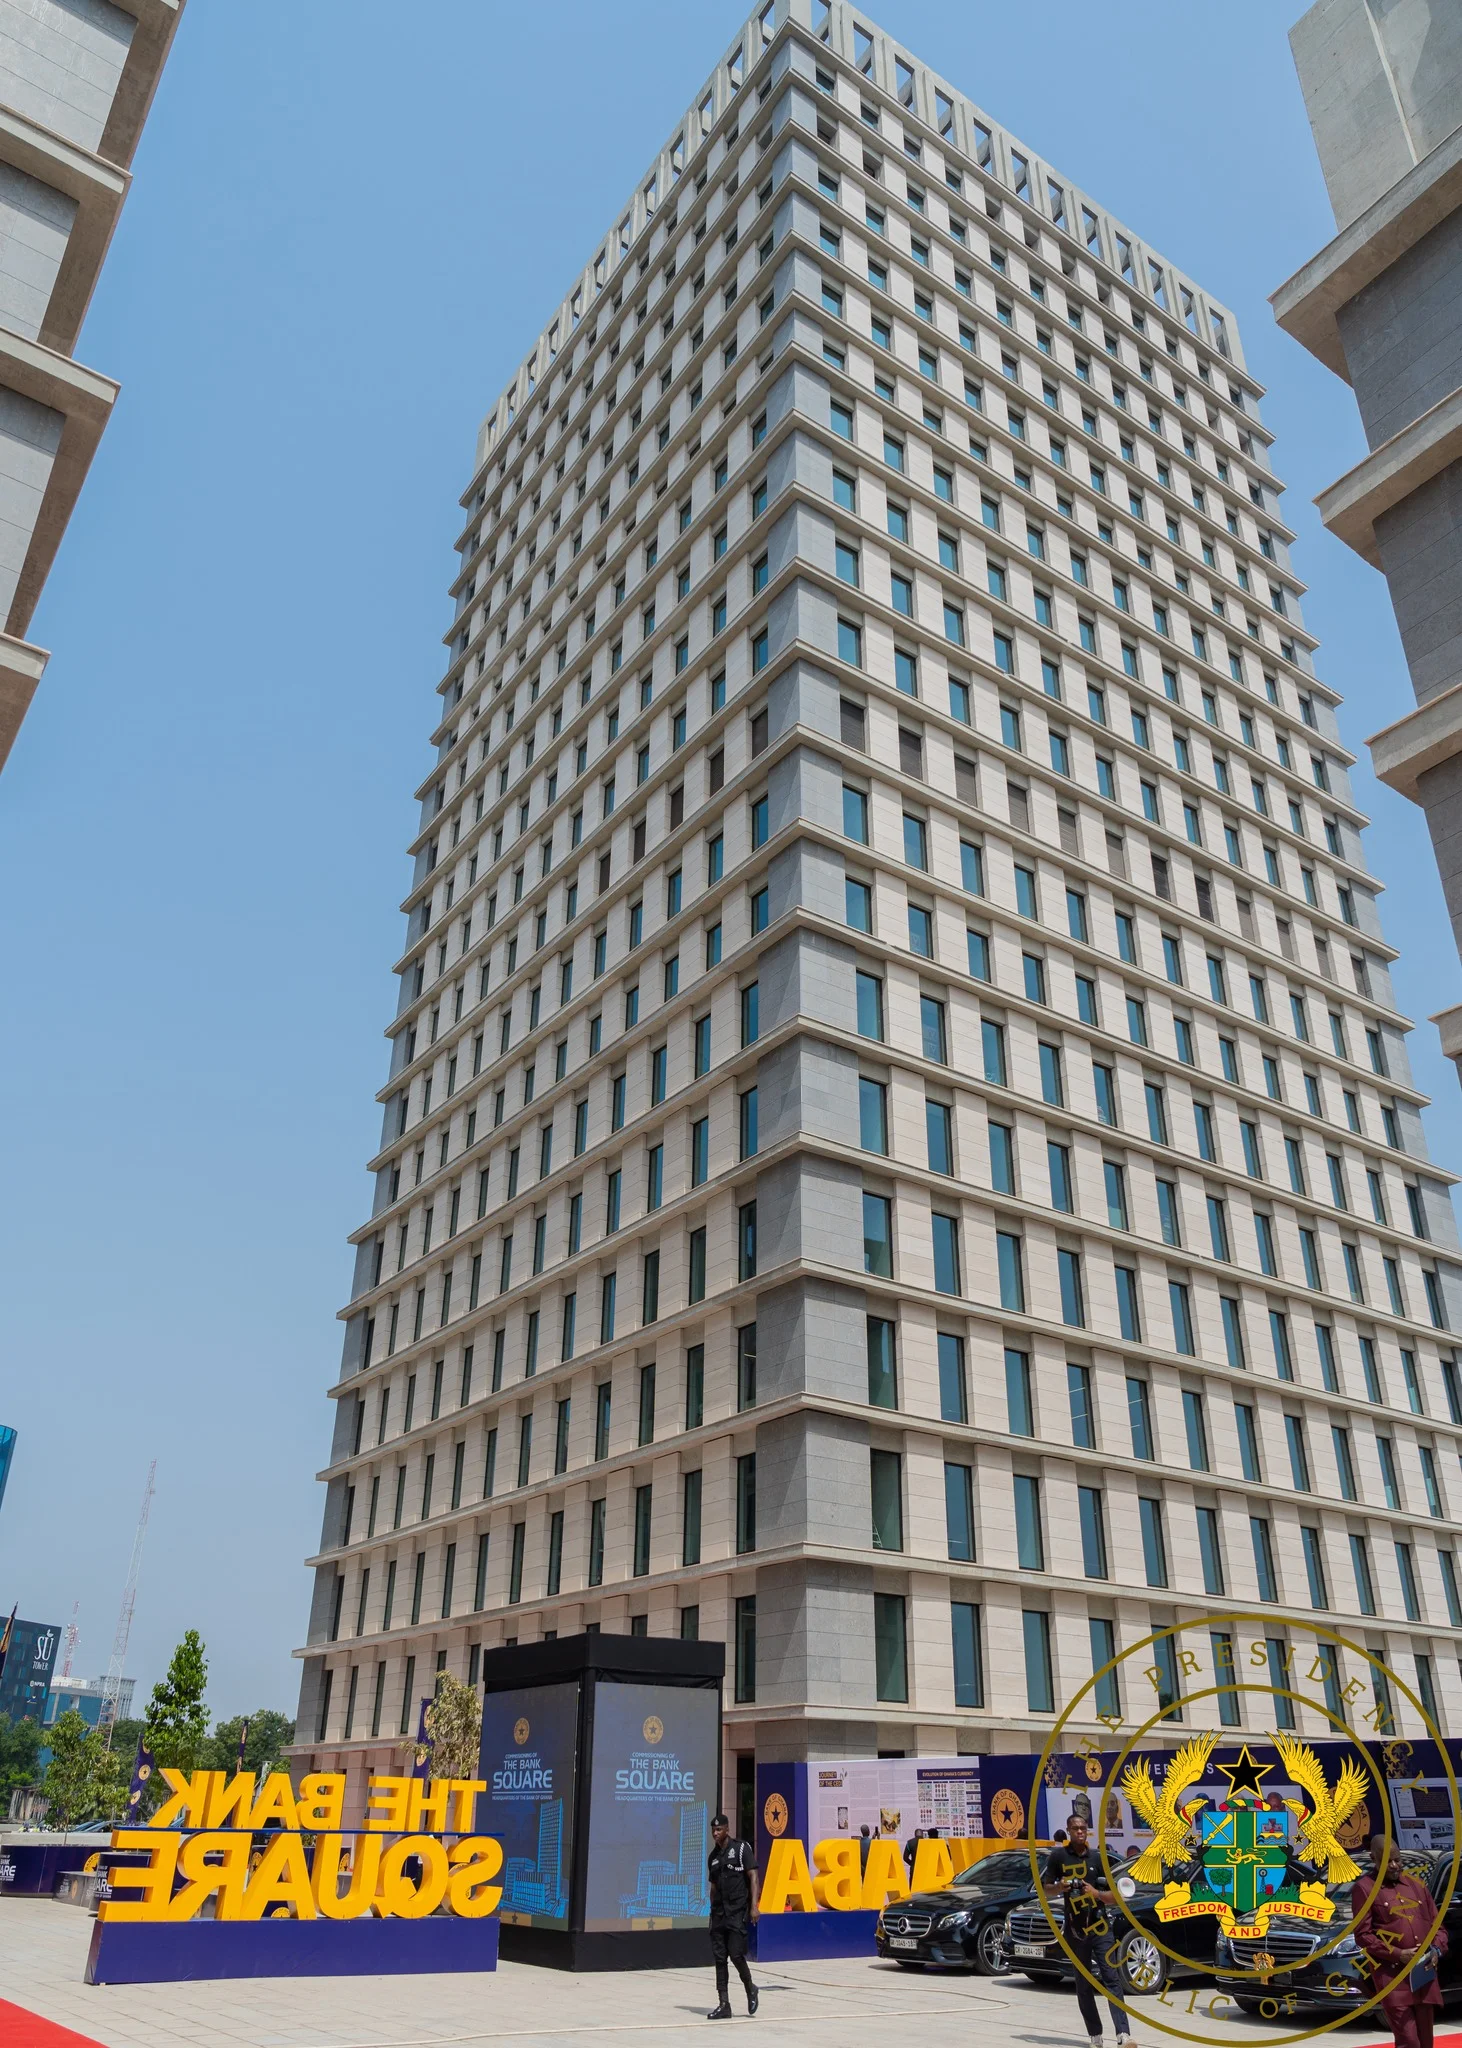
Between 2017 and 2019, Ghana's financial sector underwent a dramatic transformation that officials framed as necessary regulatory reform, but which left thousands jobless and raised questions about political motivation. The period saw the revocation of banking licenses, the collapse of microfinance institutions, and the consolidation of assets into state-backed entities—a process that fundamentally reshaped Ghana's indigenous financial landscape.
The stated objective was clear: eliminate systemic weaknesses, enforce corporate governance standards, and create a smaller number of well-capitalised banks capable of financing major national projects in oil, gas, and mining. However, critics, affected shareholders, and industry observers have questioned whether the exercise functioned as intended regulatory reform or as a calculated redistribution of wealth and market control.
The Scale and Timeline of the Closures
The process began on 14 August 2017, when the Bank of Ghana revoked the licenses of UT Bank Ltd and Capital Bank Ltd. Their deposits and prime assets were transferred to state-owned GCB Bank Ltd, with PwC receivers overseeing the liquidation process. This initial action set the pattern for what followed.
Between 2018 and 2019, the closures accelerated dramatically. uniBank Ghana Ltd, The Royal Bank Ltd, Beige Bank Ltd, Sovereign Bank Ltd, and Construction Bank Ltd were all collapsed into Consolidated Bank Ghana (CBG) Limited. More significantly, over 370 microfinance, microcredit, and savings and loans companies were systematically shut down, often with minimal warning to depositors and stakeholders.
The consolidation programme ostensibly aimed to create stronger financial institutions, but the scale of closures—particularly affecting smaller, indigenous institutions—raised concerns about selective targeting.
The Human and Economic Toll on Ghanaians
Beyond regulatory documentation and financial metrics, the closures produced devastating consequences for ordinary Ghanaians:
- Employment losses: Over 20,000 direct and indirect jobs were eliminated across banks, savings and loans firms, and microfinance institutions, throwing banking professionals, tellers, loan officers, and corporate staff into sudden unemployment.
- Microfinance collapse: The shutdown of microfinance companies crippled the informal sector. Small business owners, market traders, and local entrepreneurs lost access to micro-credit, triggering cascading business closures and widespread poverty in communities dependent on these services.
- Depositor hardship: Millions of Ghanaians were unable to access their savings, pensions, and working capital for extended periods. Documented cases of health crises, family breakdowns, and severe personal distress followed the prolonged lockdown of funds.
- State financial burden: Rather than generating savings, the government issued tens of billions of GHS in bonds to fund bailouts, transferring the cost of the restructuring onto taxpayers.
Why It Matters for Ghana: Questions of Political Economy and Accountability
The financial house cleaning remains politically contested in Ghana because fundamental questions remain unanswered. Were the targeted institutions genuinely insolvent threats to system stability, or were some viable institutions selectively liquidated? Why did state-backed and politically connected entities preferentially acquire assets and customer bases from collapsed banks, rather than those assets being restored to original shareholders or distributed through competitive auction?
The current administration under President John Dramani Mahama and Finance Minister Dr. Cassiel Ato Forson faces pressure to audit the 2017–2019 period. Public accountability requires clarity on: the role of BoG officers and Ministry of Finance officials; the conduct of PwC receivers and forensic auditors; the criteria used to select which institutions were rescued versus liquidated; and whether political alignment influenced regulatory decisions.
For ordinary Ghanaians who lost jobs, savings, and livelihoods, the distinction between regulatory necessity and political purge carries profound moral and economic weight. Any future financial restructuring will require transparent criteria, protection for depositors, and genuine alternatives to mass liquidation if public confidence in Ghana's financial system is to be restored.
The debate reflects a broader tension in Ghana's development: whether state intervention in markets serves genuine public stability or redistributes wealth in favour of politically connected actors at the expense of indigenous entrepreneurs and working Ghanaians.
Source: Today GH

Comments (0)
Be the first to comment.