
Zenith Bank Ghana Urges SMEs to Build Disaster-Proof Businesses Amid Economic Recovery
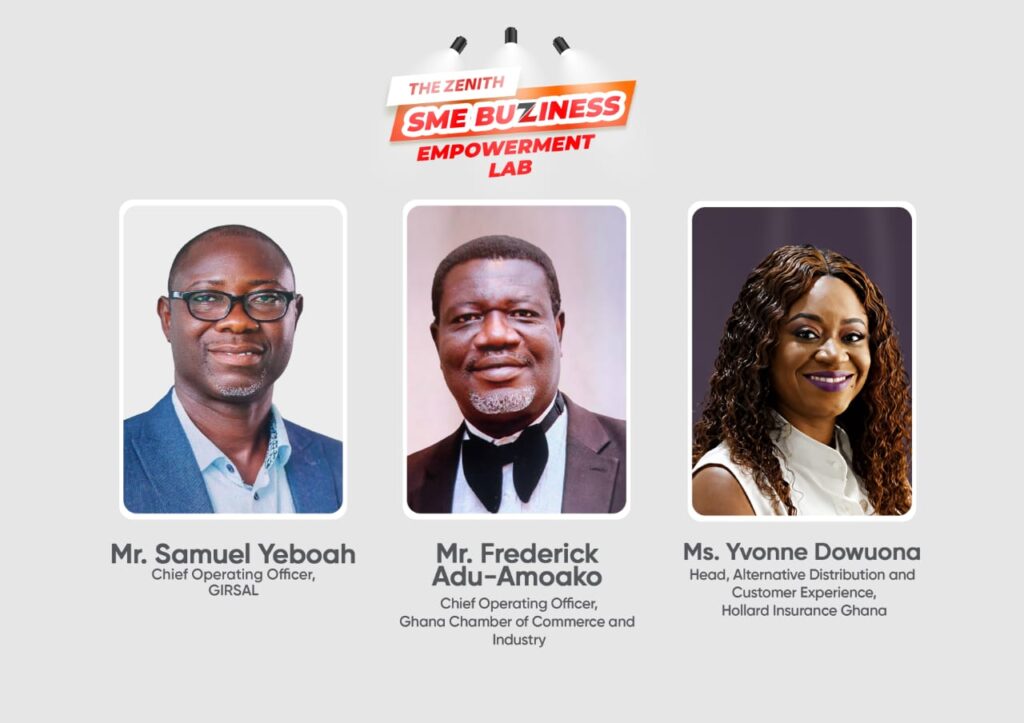
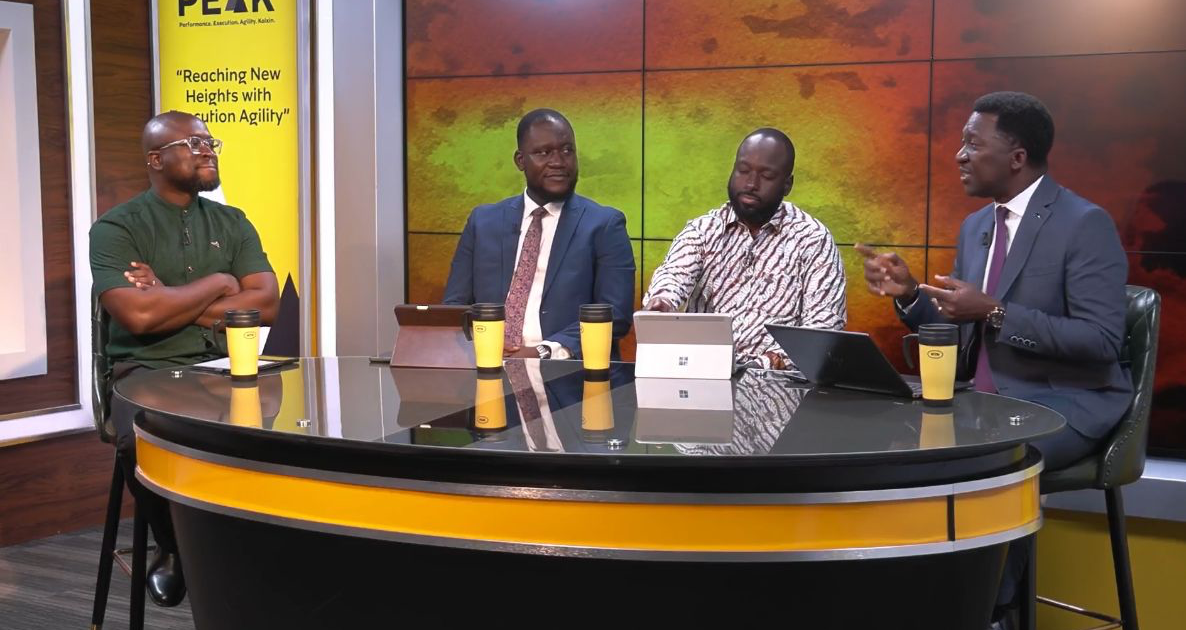
Small and medium-sized enterprises (SMEs) across Ghana have received a timely warning: without deliberate risk management strategies, even profitable businesses can collapse when disaster strikes. That was the central message at the third edition of Zenith Bank Ghana's SME Business Empowerment Lab, held virtually under the theme "Building a Resilient and Disaster-Proof Business." The webinar brought together senior voices from banking, commerce and insurance to equip Ghanaian entrepreneurs with practical tools for long-term survival.
Six Red Flags Every Ghanaian SME Owner Should Know
Samuel Yeboah, Chief Operating Officer of the Ghana Incentive-Based Risk-Sharing System for Agricultural Lending (GIRSAL), opened with a sobering assessment of the vulnerabilities facing Ghanaian SMEs. He grouped the most common business risks into two broad categories: internal and external.
On the internal side, he flagged poor cash flow management, mounting debt, inadequate record-keeping and weak governance as the most damaging threats that businesses often ignore until it is too late. Externally, he pointed to overdependence on a single buyer or supplier, unmanaged climate-related threats and declining product quality as risks that can swiftly derail operations.
For agricultural SMEs in particular — a significant segment of Ghana's small business landscape — Mr. Yeboah noted that climate shocks, rising production costs, delayed buyer payments and biological hazards pose serious operational threats. He was especially firm on the danger of relying on one customer or supplier, urging entrepreneurs to diversify their business relationships as a matter of priority.
His recommended approach to resilience involved five practical steps: identifying the most critical risks facing the business, assessing their financial impact, developing appropriate responses, assigning clear staff responsibilities and scheduling regular reviews of contingency plans.
Why It Matters for Ghana
Ghana's SME sector is widely regarded as the backbone of the national economy, accounting for a large share of employment and domestic output. Yet the sector has historically been fragile — exposed to currency depreciation, inflation spikes, unreliable power supply and shifting regulatory environments. The economic turbulence of recent years, which saw inflation surge and the cedi lose significant value, wiped out many small businesses that had no financial buffer or crisis plan in place.
Frederick Adu-Amoako, Chief Operating Officer of the Ghana National Chamber of Commerce and Industry (GNCCI), acknowledged that the economic picture is now improving — with inflation declining and Treasury bill rates easing — but cautioned that this breathing room should be used wisely. He urged entrepreneurs not to relax during good times but to use periods of stability to strengthen their defences against the next wave of disruption.
Mr. Adu-Amoako identified natural disasters, cyber threats, supply chain disruptions, reputational damage and regulatory challenges as risks that Ghanaian businesses must actively plan for. His practical suggestion was straightforward: every business, regardless of size, should have a simple one-page crisis management plan listing potential threats, essential operations, emergency contacts and staff roles during a crisis. He also emphasised the importance of backing up financial records and ensuring staff know what to do in an emergency.
The GNCCI, he added, continues to support SMEs through advocacy with government and regulatory bodies, capacity-building programmes, business networking events and facilitating access to new markets.
The Role of Insurance in Protecting Your Business
Yvonne Dowuona, Head of Alternative Distribution and Customer Experience at Hollard Insurance Ghana, rounded out the discussions with a focus on insurance as a frontline risk management tool that remains underutilised by most Ghanaian SMEs.
She urged business owners to properly value their assets and select insurance policies that genuinely match their risk profile — covering property, business operations, liabilities and even the lives of key personnel. Many SME owners, she noted, either underinsure or take out policies without reviewing them as the business grows, leaving significant gaps in coverage.
- Accurately assess the replacement value of all business assets before choosing a policy.
- Review and renew insurance coverage annually as your business evolves.
- Ensure policies cover liabilities and business interruption, not just physical assets.
The Zenith SME Business Empowerment Lab series represents a growing effort by the bank to go beyond lending and actively support the capacity and resilience of Ghana's small business community. For entrepreneurs watching Ghana's economic recovery with cautious optimism, the message from all three speakers was consistent: now is the time to prepare, not wait.
Source: MyJoyOnline

Comments (0)
Be the first to comment.